Loan Management Software in Kenya
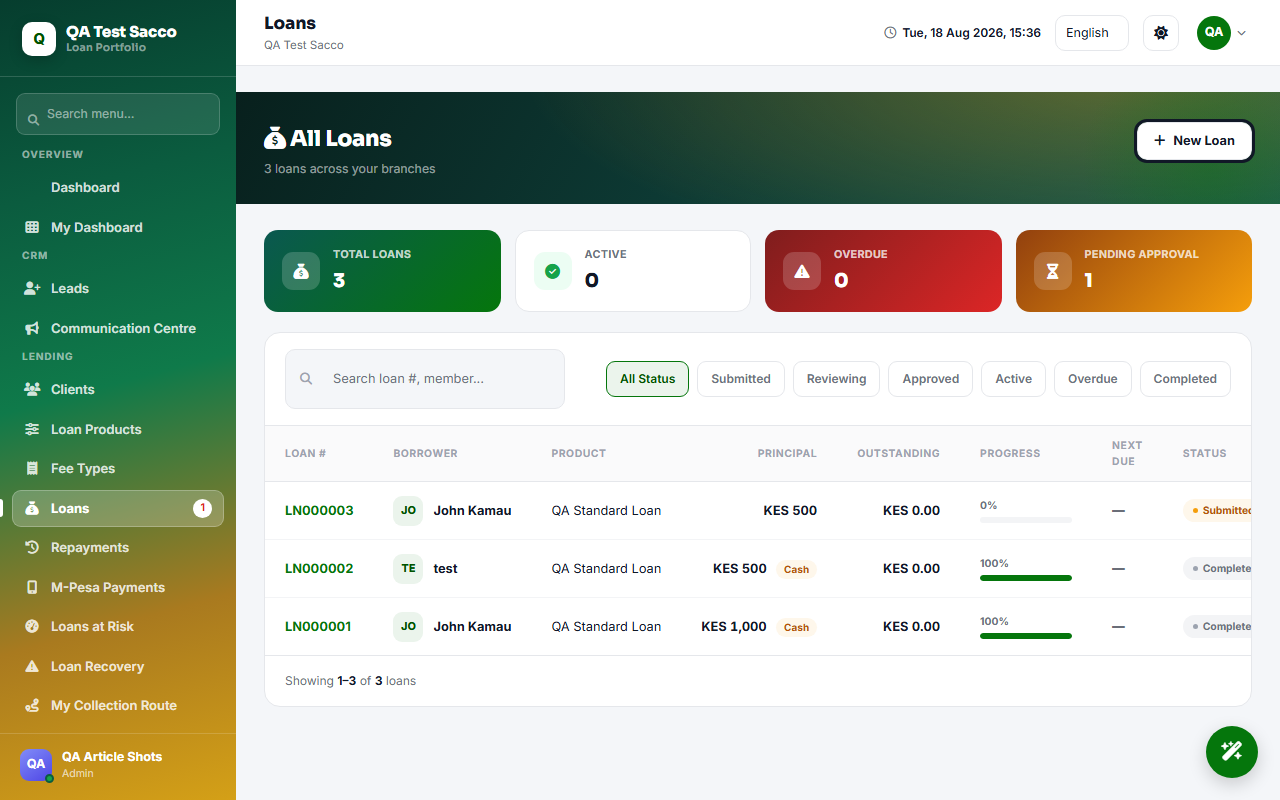
Every organisation that lends money, whether it's a SACCO, a chama, a microfinance institution, or an employer running a staff loan scheme, ends up solving the same underlying problem: tracking who applied, who was approved, how much was disbursed, what the repayment schedule looks like, and what's actually been paid back versus what's still owed. Loan management software exists to handle that lifecycle reliably, at whatever scale the lender operates at.
A proper system starts before disbursement, with the application and appraisal stage: capturing the request, checking eligibility (often tied to a borrower's savings, shares, or credit history), and routing it through whatever approval steps the lender requires, a single approver for a small chama, multiple sign-off levels for a larger SACCO. Interest calculation is where a lot of informal lending goes wrong, a system needs to support both flat rate and reducing balance methods correctly, since the two produce materially different real costs for what looks like the same stated rate, and generate the repayment schedule automatically rather than leaving it to a spreadsheet formula someone wrote once and never re-checked.
Once a loan is disbursed, the software's job shifts to tracking repayments against that schedule, installment by installment, and flagging arrears the moment a payment is missed rather than at month-end reconciliation. Guarantor and collateral tracking matter here too, if a borrower defaults, the lender needs to know immediately what security is actually behind that loan, not dig through paper files to find out.
Good loan software also produces the reports a lender actually needs to run the business, portfolio at risk, arrears aging, disbursement trends, and each borrower's real-time balance, without someone manually combining spreadsheets from different stages of the loan lifecycle.
pawa Loans runs this full lifecycle, application through appraisal, approval, disbursement, repayment, and arrears, for SACCOs and chamas on one connected platform, so a lender isn't stitching together separate tools for each stage of a loan's life.
Frequently asked questions
Who uses loan management software?
SACCOs, chamas, microfinance institutions, and any organisation that lends its own members' or clients' money and needs to track applications, repayments, and arrears reliably.
What does loan management software actually track?
The full lifecycle, applications, appraisal, approval, disbursement, the repayment schedule, actual repayments received, and any resulting arrears, tied back to each borrower.
Can loan software calculate interest automatically?
A proper system should support both flat rate and reducing balance interest and calculate the repayment schedule for either automatically, rather than requiring manual amortisation tables.
Ready to run your SACCO, chama, or microfinance from one dashboard?
Get started