SASRA Compliance for Deposit-Taking SACCOs: What You Actually Need
The moment a SACCO starts taking withdrawable deposits rather than just managing shares and locked-in savings, it becomes a deposit-taking SACCO (DT-SACCO) and falls under the Sacco Societies Regulatory Authority, SASRA. That's a materially bigger compliance obligation than a non-withdrawing SACCO carries, and it doesn't stop at a one-time license application.
The headline requirements are prudential ratios: minimum core capital, a core capital to total assets ratio, and a core capital to total deposits ratio, all of which SASRA expects a DT-SACCO to maintain on an ongoing basis, not just at the point of licensing. Falling below them isn't a paperwork issue, it can trigger regulatory intervention.
Beyond the ratios, SASRA requires regular statutory returns, periodic financial statements built on real, auditable figures, and a governance structure that keeps board oversight separate from day-to-day management. In practice, all of that traces back to one thing: whether the SACCO's underlying books are accurate enough to produce those figures on demand, not reconstructed under deadline pressure from scattered spreadsheets.
This is where a lot of SACCOs quietly struggle. It's possible to run day-to-day operations on manual records for a while, but the moment a SASRA return is due, someone has to reconcile savings, shares, loans, and provisions into figures that actually tie out, and errors found at that stage are far more expensive to fix than errors caught in real time.
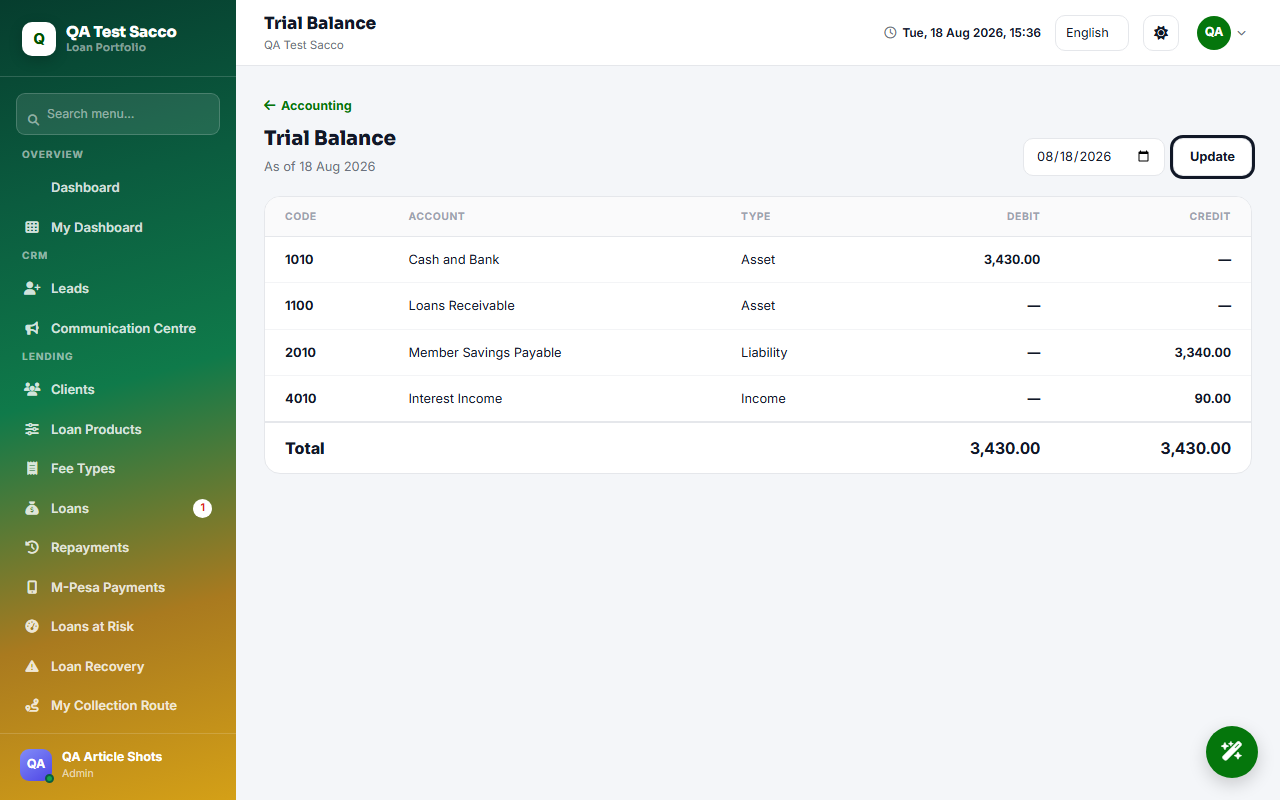
pawa Loans posts every transaction through a real double-entry ledger the moment it happens, so the numbers a SASRA return needs, core capital, deposits, loan portfolio, provisioning, are already correct and current rather than something to be assembled under deadline the week a return is due.
For the current SACCO Societies Act, regulations, and MIS/reporting guidance, see SASRA's official website directly rather than relying on any vendor's compliance claims, including ours.
Frequently asked questions
What triggers SASRA oversight for a SACCO?
Taking withdrawable deposits. A SACCO that only manages shares and locked savings isn't a DT-SACCO and doesn't fall under SASRA.
What are the headline SASRA requirements?
Prudential ratios, minimum core capital, core capital to total assets, and core capital to total deposits, maintained on an ongoing basis, not just at licensing.
What usually goes wrong for SACCOs that struggle with SASRA returns?
Books that aren't accurate enough to produce the required figures on demand, forcing a rushed reconciliation under deadline pressure when a return is due.
Ready to run your SACCO, chama, or microfinance from one dashboard?
Get started